Opportunities for Hybrid AC-DC Infrastructure in India

India stands strong in achieving universal access to electricity with almost 100% electrification by 2019. The national grid has played a very important role in improving this access, but its reliability continues to pose a challenge, and more so in semi-urban, rural and remote areas. Distributed Renewable Energy (DRE) in the form of solar roof tops (SRT) and solar home systems (SHS) tied with efficient appliances help improve reliability of service and are seeing increased adoption. By some estimates, there are approximately 4 million HHs (1.4% of the total 277 million HHs in India) with some form of SRTs or SHSs in India.

Many of the previously used SHSs were standalone systems powering AC and/or DC Appliances with energy storage. Today, there is a new class of DRE solutions commonly termed Hybrid Solar Systems, which integrates solar with AC grid power (uni or bi-directional) and can power AC and/or DC appliances. Such new Hybrid AC-DC (HAD) power solutions can help users to take advantage of solar power – improving supply hours and reducing their Power Distribution Company (Discom) energy bills. India saw estimated annual sales of some 0.8 million units of solar hybrid inverters or uninterruptible power supply (UPS) systems in 2019 (compared to some 8 million-unit sales of conventional inverters) and there is an expected increasing trend.

More and more power systems and appliances OEMs and System Integrators are joining this fast-growing HAD market in India. There is a new class of efficient appliances (including lights, bulbs, fans, TVs, refrigerators, washing machines, pumps, etc.) that use fundamental DC-run LED or BLDC motors, and can be run on AC supply and/or DC supply. Some further innovations in appliances include embedding energy storage inside the appliance to avoid the need for costly centralized power back-up solutions. These innovations on the appliances side will further push for increased need of enabling HAD infrastructure for the synergistic co-existence of AC and DC.

In this regard GOGLA initiated a whitepaper which evaluated the opportunities for HAD infrastructure in India. The paper evaluates potential customer segments expected to drive the demand for HAD solutions. The demand assessment identified HHs with no power back-up solution, potential HHs with grid-connected solar rooftops, existing conventional inverter customers, existing mini/micro grid customers and existing SHS users as the potential customer segments to transition hybrid solar systems.This paper also suggests three key strategies to enable these customer segments HHs to shift to HAD power solutions as below:

  • Strategy-1: Upgrading existing power back-up solutions
  • Strategy-2: Adding new HH that do not have any power back-up solution
  • Strategy-3: Replacement at end of product life

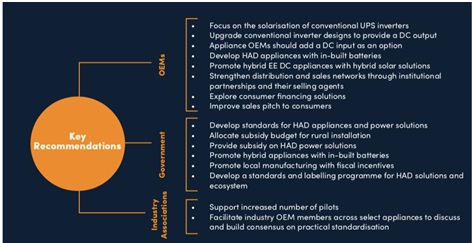
To further strengthen the HAD infrastructure in India, below key recommendations were made to the OEMs, Government and Industry Associations. The findings of the study were shared through an online webinar along with industry experts.
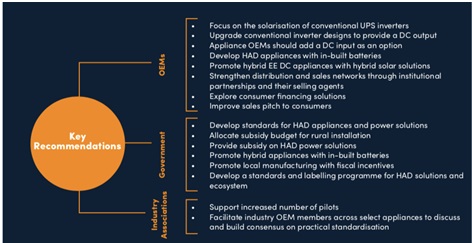
During the launch event, Padmashri Prof. Ashok Jhunjhunwala stated small (<1kW) and large (>3kW) size of HAD power solutionwhich can also feed solar power back to grid can be designed at low-cost and scaled-up. It has immense potential to cover every home in India. He also emphasized that there is a need for remote monitoring, data analytics and controls to designsuch HAD system which will ensure there is no wastage of solar power, minimum usage of AC grid power and at the same time have sufficient power back-up.

Shiva Srivastava, Marketing Leader Asia from Greenlight Planet converged on the thoughtthat HAD is a very promising technology and futuristic as lot of homes are getting connected to grid and already using SHS. Venkat Rajaraman, Chairperson GOGLA India Working Group highlighted the strong need of hybrid AC-DC infrastructure as there is proliferation of EE DC appliances and grid extension. He also mentioned that he views HAD technology for residential sector would fit well and also be a big opportunity area for HAD power solutions.

Rajesh Kunnath, Radiostudio and Convener IEEE LVDC Standards said there are many gaps in standards and there has to be reports like this which act as a backbone to understand HAD architecture and credible market opportunity that is scalable. This will energize the standards body and pave way for manufacturers to participate in standardization to improve reliability. Adding to this Makena Ireri, Manager from CLASP highlighted that it will be important to facilitate R&D and pilot demonstrations as they help bringing more market players and bringing down the technology costs.

Acknowledging the study, Koen Peters, Executive Director, GOGLA mentioned that the research has come very timely as there are developments in industry with EE DC appliances and hybrid solar systems. He also stated that standardization may be a driver to innovation, and it would be wise for the industry to come up with the ideas as to what needs to be standardized and in what ways, before bringing it to BIS or IEEE to have a better direction to promote innovations.

It was concluded by Rahul Bagdia, Managing Director, pManifold that evidently the market is heading towards hybridization, i.e. integration of AC-DC power supply and appliances that support these systems. However, challenges like high upfront equipment cost, high sales effort, low customer awareness, and lack of standardization are an acknowledged reality. Yet, these factors should not deter off-grid players from diversifying and offering HAD solutions to customers. The key industry stakeholders like OEMs, Government and Industry Associations will play a vital role towards mitigating these challenges and enabling growth of HAD infrastructure in India.
Download Report

Distribution Power Franchisee – Evolving PPP model

Distribution Franchisee (DF) model has only recently picked traction since 2009 after successful demonstration by Torrent Power Ltd. at Bhiwandi, Maharashtra, which got operational in 2007. The success there has sparked private businesses interest into the sector with more than 30 corporates jumping into the fray.

Many of the businesses comes from very diverse background of telecom, IT, infra, media, iron & steel etc. and it will be there new entry into the power sector, starting with distribution.

The emerging nature of the DF model, high return promise, low entry barriers, closer to end-consumers, focused high capex with predictable cash flows and easy financial leverage under energy efficiency are some of important investment attractors.

The risks of operationalization of DF are still getting unearthed with less than 3-5 implementors. Most businesses are intuitively betting on capitalising the high ATC losses in range of 30-50% in DF selected areas. The 15-20 years DF contracted period with estimated 4-5 years to bring losses to range of 15% makes viable ROI.

While the credibility of delivery from new players is still to be tested, there stands a strong chance of these new players bringing professionalism, technology, IT, measurements driven performance, analytics, strong SLAs (Service Level Agreements), and much forgotten customer focus back to the utility business.

Under light of this, is DF a good PPP model? Does it has potential to scale? We will continue sharing our views and also from best industrial experts on this in coming articles under label of ‘Smart Distribution’.

Post by: Rahul Bagdia @ pManifold.

What’s there in Distribution Power Franchisee?

With ongoing operationalization of Distribution Franchisee (DF), one common question that keeps hitting again and again is ‘Why need of DF? What it can do, which utility cannot or have not?’. While answer to this is pretty subjective, I would share my opinion in 3 breakups

Key issues that are affecting profitability of distribution utility

  • What are key issues with Distribution Utilities?
  • How that has constrained key stakeholders potentials?

Does Distribution Franchisee has solutions to above?

  • Link from Measurements (MIS) to Effective Distribution Management missing
  • Lack of Incentivization
  • PSU Organizational Constraints
  • No Investment in skill enhancement
  • Low Enforcement
  • Govt. hindrance & manipulation
  • Low Accountancy

Key stakeholders revenue potential constrained with missing last-mile robustness

  • End consumers not getting reliable, sufficient and rightly priced power
  • Generators unable to get guaranteed evacuation of all generated power
  • Distributors (Utilities) themselves in losses
  • Power Traders do not have predictability
  • Does DF has a solution to above

At the end of day, it will do same thing as utility, but with a difference – more concentrated ownership that will expedite decisions to actions. Another way to look upon it will be as an extended ‘Business Outsourcing’ model, wherein the Franchisee becomes the new front end to the end-consumers, but assets still remains on book of the original Utility. The real underlying phenomenon driven by franchisee model is

  • Performance benchmarking through establishing baseline
  • Incentives alignment of all stakeholders

It is this ‘Measurements and Analytics’ that will drive the change and bring above suggested values to all stakeholders.

Post by: Rahul Bagdia @ pManifold

Real gains for Utility and End-Consumers from Distribution Franchisee business

An obvious question with so much projected on Distribution Franchisee (DF) model is:

What real gains both the utility and end-consumers could expect coming out of the Distribution Franchisee model?

While Bhiwandi implementation of Distribution Franchisee has shown increased consumer satisfaction for improved service levels, but it is yet to be proved conclusively that the model has brought any significant monetary gains to the utility. The slow emergence of a potential impactful model (distribution franchisee) amidst opposition – from utility employees and end-consumers, could be attributed to missing INFORMATION and transparency. Opposition from utility employees is obvious as DF with its flavor of privatization is based upon driving cost efficiency by increasing productivity and hence reducing on numbers of utility employees. But opposition and fear from end-consumers is little less understood, when it doesn’t matter that same power at same tariff (decided by State regulators & common to the state) comes from utility or DF. May be this fear from end-consumers has some roots in weaken regulation/enforcement or mis-information or perceived apprehensions.

In any case, going forward there are many questions, that needs clarification to smoothen resistance, but more importantly to engage all stakeholders well to co-create sustainable solutions. A few of importance are:

  1. With reduced AT&C losses from 50+% to order of 15% and reduced administrative & operations costs, could it be expected to see decreasing power tariffs (or atleast no changes for 5-10 years inspite of rise in power procurement costs) as realised by end-consumers? If and how does DF monetary gains could be shared with its end-consumers?
    • Since there is only one state level tariff plan prepared, consolidating audit reports from each circles/zones, the good and bad performances of different circles (including that of Franchisee’s) get mixed to create one tariff plan. So in such case unless more decentralization penetrates in distribution, that DF circle end-consumers cannot expect their tariff plan alone to be improved. If however DF model scales all through out the state, then combined benefits could still bring common savings to all state end-consumers.
    • Above would also mean that even if one circle’s management did a poor job of cutting its AT&C losses, there is no way of penalizing them independently. The entire state end-consumers get penalized equally. This is one serious missing incentive structure that has plagued utility’s performance.
  2. How does exactly DF implementation improves profitability of the utility?
    • What are financial calculations that local utility has to consider to make a strong case for bringing in Distribution Franchisee over business-as-usual case? What profits (if any) can utility expect by leasing out its assets for 15 years to Distribution Franchisee?
    • How does the effective cost of distribution to local utility is accounted in setting benchmark input rates and its locking for next 15 years? We only hear the price realization terms like ABR (Average Billing Rate) and tariff setting term ARR (Aggregate Revenue Requirements) in RFP, but no comparison of these with actual cost of distribution.
    • Has post DF termination and appropriate depreciation of assets already being accounted in investment decision making?
    • Is utility prepared to take charge again post DF tenure or will it re-lease another DF term or there will be full privatization?

Post by: Rahul Bagdia @ pManifold

Rural Franchisees – Could they become pilot ground to raise next level of Distribution services?

A recent publication from Prayas on ‘Rajiv Gandhi Rural Electrification Program – Urgent need for mid-course correction‘ gave a very good overview of RGGVY program, its features and progress. Some key observations made:

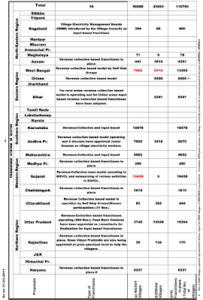
    1. Total 1.1 lakhs Rural Franchisees in India (detailed distribution given below)
      • This covers only 19% of total villages in the country including both the RGGVY and non-RGGVY villages
      • Only 38% RGGVY villages are covered under Franchisees, when all are supposed to have mandatory Rural Franchisees
      • 95% of total Rural Franchisees are Revenue Collection based Franchisees
      • Bihar, Gujarat (91%), Haryana (91%), Karnataka (73%), Nagaland, UP and West Bengal have above national average (i.e. 19%) Rural Franchisees in RGGVY villages

2. Rs. 26000 cr. already spent in last 6 years since 2005 and estimated another same amount to be spent (totaling to Rs. 52000 cr.) for coverage of RGGVY original targets of  100% village  electrification and 2.34 cr. rural BPL household connections.

      • Since 2005, 96562 villages have been electrified raising the level of ‘village electrification ’ from 74% to 91%. (Total villages in India is ~6 lacs, out of which 1.25 lacs did not have access to electricity in 2005)
      • Since 2005, 1.75 crores rural households are given new connections raising the level of ‘rural household electrification’ from 43% to 56%. (Total # of rural households in India is ~14.5 crores, out of which 7.8 crores did not have access to electricity in 2005)
    1. 3. By estimate of investment, of order Rs. 52000 cr., RGGVY scheme is comparable to R-APDRP scheme of GoI.

Rural ‘Power’ Inclusion:
As Prayas’s paper identified there has been significant progress in grid extension and household connections through RGGVY, there remain broader questions to build answers for broader rural ‘power’ inclusion:

    • Quality of work and power supply
    • Sustainability of the infrastructure
    • Contribution to local (i.e. rural) development

‘Rural Franchisees’ is definitely one key to unlock rural power inclusion in India. There is strong need to innovate & integrate ‘Distribution/Delivery’ of power with:

    • Local ‘Distributed Generation’ of power
    • Strong policy initiatives to allow better grid interaction/sharing and localised tariff setting
    • Strong governance and independent monitoring of customer satisfaction

Market Opportunity comparison:

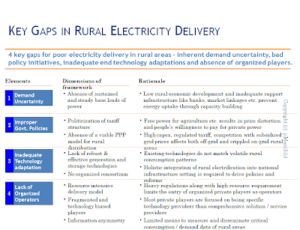
A simple comparison of the ‘existing’ market size (both in terms of numbers and contract values) of Distribution Franchisee opportunities between Rural and Urban, seems to point Rural as a winner. However challenges remains with some key gaps identified below in delivering rural electricity.

Question is what could be learnt from solving these ‘rural’ specific challenge with so much investment already gone into it and still more to come? What will be the applicability of those learning to broader Power Distribution markets? Could that lead to ‘disruptive innovation’ for improving financial health of utilities in India and improve Distribution efficiencies? Who amongst private players will bring that ‘market inflection’? Will the teachings of late Prof. C.K. Prahalad on ‘Fortune at the bottom of pyramid’ be applicable to this sector and who will set the first path?

One possible Strategy for entry into Distribution Franchisee:

There are already great efforts from many new players to enter into upcoming Distribution Franchisee bids (at district level like as in Madhya Pradesh) and they face tough competition against tough terms and conditions (like high ‘reserve rates’, strong qualification criterion, high EMD & security deposits etc.). It is possible that these new entrants or even established private companies also consider building first hand experience from participating in lower capital risk Rural Franchisees and bring their private corporate management best practices to establish reforms and innovations. With 1.1 lakhs rural franchisees and that covering only 19% of total villages and already invested Rs. 26000 crores, this could provide an easy and fastest entry to build most direct experience in the sector and participate in bigger bids more strongly, with more experience and hopefully at lowest rates with best workable technology.

Not to say that the Rural Franchisee experience would be easier than any urban franchisee or to be treated with less care. Infacts as highlighed above, the odds are higher in rural region and demands innovation. But the one who can cracks this rural challenge of power distribution will definitely emerge as a leader in this space with direct mapping of his skills set to urban challenge, but not the vice-versa for its otherwise competitors. Recent upsurge of ‘mobile’ market and ‘financial inclusion’ in rural are clear examples, that even in POWER sector, its time to offer more ‘choices’ to the end-customers and specially ‘Rural consumers’ be looked upon as profitable and respected segment (See earlier blog – Why Customer’s Satisfaction & Preferences are important for Electricity Utilities?).

A shift from Rural-to-Urban-to-Rural will soon begin – See earlier blog Power Distribution Franchisee – Evolution from Rural to Urban and back to Rural.

At pManifold, we intend to undertake more detailed gap analysis with operating Rural Franchisees and help them Organize-Manage-ScaleUp. Interested stakeholders with willingness to support this cause and study, please contact Rahul Bagdia @ rahul.bagdia@pmanifold.com (+91 95610 94490)

Post by: Rahul Bagdia @ pManifold

Solar PV System Workshop -Technology, Risks, Manufacturing, EPC, O&M and Investment

pManifold as Knowledge Partner to IIES 2011 organized a workshop on ‘Solar PV System – Technology, Risks, Manufacturing, EPC, O&M, Investment’. The workshop brought best Industry experts and participants through out the country.

pManifold Indis_Solar PV_IIES_Workshop_report

https://www.slideshare.net/slideshow/embed_code/7293704

View more presentations from pManifold

Topics and brief content covered in the workshop

  1. Grid connected (MW Size) Solar PV plants
    • What it is & current players
    • Key challenges (Land / Technology / Competition)
    • Innovation – as a key strategic advantage
    • Role of components: Modules, Inverters, Racking, Trackers, Processes. How each of them play a crucial role in Levelised Cost of Energy (LCOE)
    • India specific challenges & Trends
    • PPAs & what are they good for
  2. Solar Module Manufacturing
    • Different  type of Solar Cells
    • How mono/multi crystalline modules is manufactured
    • Composition of modules
    • Machines required for manufacturing
    • Process of manufacturing
    • Testing of Solar Modules / Standards & Certifications
    • Important aspects in Module manufacturing
    • Investment and rough estimation on cost of project
    • Rough estimate on cost of manufacturing
    • Central & State Govt. Incentives – How to choose the right location
  3. Financing Solar/RE – Bankers Perspective
    • What is the mindset of a Banker (from a risk point of view)
    • How should a Project Promoter think towards De-Risking a Project Proposal
    • Is there an ideal Equity/Debt mix that is better and more attractive from a Bankers perspective (will increase the financing chances)
    • What are the key decision makers / departments in SBI that will handle Renewable Project Finance
    • What is the typical timeline associated with a Project Finance Proposal (avg. time between receiving a proposal and release the first tranche of funds)
  4. Off-Grid / Rooftop Solar Solutions for Buildings
    • Sourcing of components: please outline what are the best sources / companies for buying other (non-PV) components (Racking / Inverters / Cables / Junction Boxes / Monitoring)
    • Price trends for 2010-2011 — any geographical trends within India (North India vs. South, East, West)
    • Rupees per Watt – how does that change for a 1 KW system vs. 10 kw system vs. 100 KW system
    • Should one go for the lowest cost PV panel available in the market
    • Prevalent payment terms in the Industry (upfront / on delivery / on installation)
  5. Consumer products –  applications and potential
    • Examples of product
    • Current cost per unit installed
    • Approximate Breakdown of the cost
    • In what circumstances are they economical
    • Subsidies, if any
    • How easy is the installation process
    • Lifetime, Reliability and Servicing issues
    • Field Experiences – What Customers say

Speakers of the workshop

Akash – CEO, Indis Energy
K.E. Raghunathan – MD, Solkar Solar Industries Ltd.
Abhijit Chakravarti – AGM, State Bank of India
Rahul Bagdia – Director, pManifold Business Solutions
Adithya – R&D Head, Intelizon Energy Pvt. Ltd.

The workshop was organized under pManifold’s Stakeholder Engagement services. Focussed emerging models with potential to solve Indian power sector challenges were selected in categories of Distribution, Conservation and Generation. Relevant stakeholders including service providers, businesses, investors, bankers and professionals including students were brought together to participate in discussions led by domain experts to come with action items to scale respective business models. More details on each workshops on our Insights page.

Post by: Rahul Bagdia @ pManifold

Key Solar Players in India in Solar Cell & Module manufacturing

The guidelines for second batch under Phase I of Jawaharlal Nehru National Solar Mission (JNNSM) were announced recently by Ministry of New and Renewable Eneergy (MNRE) . The excerpts of the guidelines are captured in our previous blog.

To give strong impetus in promoting domestic manufacturing, the developers are expected to procure their project components from domestic manufacturers. For Solar Photo-voltaic (PV) projects using Crystalline technology, to be selected in second batch during FY 2011-12, it is mandatory for all the projects to use cells and modules manufactured in India. However, Thin film and Concentrated PV (CPV) has no such domestic limitations.

In view of the above, the list of major Indian players in Solar Cell and Module manufacturing along with Technologies are mentioned below:-

Sr. No.Company NameSolar CellsSolar ModulesCrystalline SiliconThin Film
1Moser Baer PV Pvt. Ltd.YesYesPolysiliconAmorphous-Silicon
2Titan Energy Systems Ltd.–YesMonosilicon & PolysiliconAmorphous-Silicon & Copper Indium Gallium Selenide
3Maharishi Solar Technology Pvt. Ltd.YesYesPolysilicon–
4Tata BP SolarYesYesMonosilicon & Polysilicon–
5Solar SemiconductorsYesYesMonosilicon & Polysilicon–
6Central Electronics Ltd.YesYesMonosilicon–
7BHELYesYesMonosilicon–
8Lanco Solar Pvt. Ltd.YesYesMonosilicon & Polysilicon–
9Signet Solar–Yes–Amorphous-Silicon
10Webel SolarYesYesMonosilicon–
11IndosolarYes–Monosilicon & Polysilicon–
12PLG Power Ltd.YesYesPolysilicon–

The above list may not be a complete and comprehensive list, but it gives an overall and fair representation of players involved in manufacturing of solar cells and modules.

  • What is to be seen if the domestic content constraint on Crystalline technology and its relative higher costs compared to Thin film will force new projects to go with Thin film technology
  • Also there will be competition amongst Crystalline panel manufacturing players to get share of batch-2 projects and this could drive new market dynamics

pManifold as part of its Solar practice offer services to properly reveal and pen down the technology, cost and performance trade-offs. (See pManifold services in Solar for more details)

Existing grid connected Solar PV Plants in India

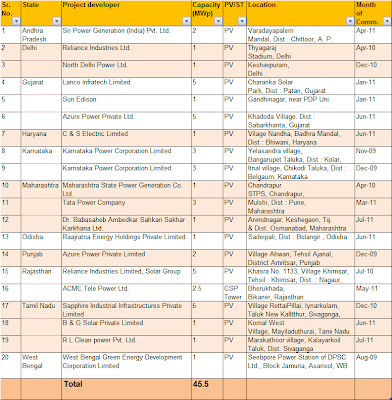
MNRE has recently released the list of all grid operating solar PV projects in India (latest updated as on July 2011. See the detailed list here and also below).

The Project Developers for these cumulative 45.5MW capacity plants were:

  1. Sri Power Generation (India) Pvt. Ltd.
  2. Reliance Industries Ltd.
  3. North Delhi Power Ltd.
  4. Lanco Infratech Limited
  5. Sun Edison
  6. Azure Power Private Ltd.
  7. C & S Electric Limited
  8. Karnataka Power Corporation Limited
  9. Karnataka Power Corporation Limited
  10. Maharashtra State Power Generation Co. Ltd.
  11. Tata Power Company
  12. Dr. Babasaheb Ambedkar Sahkari Sakhar Karkhana Ltd.
  13. Raajratna Energy Holdings Private Limited
  14. Azure Power Private Limited
  15. Reliance Industries Limited, Solar Group
  16. ACME Tele Power Ltd.
  17. Sapphire Industrial Infrastructures Private Limited
  18. B & G Solar Private Limited
  19. R L Clean power Pvt. Ltd.
  20. West Bengal Green Energy Development Corporation Limited

With increasing Solar EPC and manufacturing experience building in Indian players, MNRE has also published a performance report on 6 grid connected power plants in India. The report parameterize some performance parameters like:

  • Technology
  • Actual Generation (in kWhs) – total, month wise
  • % Capacity Utilization Factor- CUF (Average over period of operation, Maximum, Minimum)

Some key observations made:

  • Avg CUF or Plant Load Factor (PLF) across the year is in range of 15-19%
  • Peak CUF occurs in March to May and range from 20.21% to 23.63%
  • Grid synchronization takes 2-4 months initial settling period with CUF going down to less than 10%

The report is first good step in monitoring performance and stakeholder engagement. However a big leap in monitoring solar plants performance and integrating the analytics to design appropriate solutions has to still happen.

Post by Rahul Bagdia @ pManifold

Key Comparative findings from Customer Satisfaction Survey of Shajapur, Ujjain & Dewas districts of MP

A comparative view of top level findings is shown here, developed using the location specific reports of Shajapur, Ujjain & Dewas available here along with 6 other districts in Madhya Pradesh (MP).

See our earlier blog:

The analysis shows that in the above 3 districts, a substantial percentage of dissatisfaction in

Customers is coming due to 2 factors, namely ‘Communication’ & ‘Price’.

The overall Satisfaction score on being computed(on scale of 0-100 with 100 being all respondents ‘very satisfied’):

CommunicationPrice
Shajapur33.6830.76
Ujjain27.0932.77
Dewas24.5020.90

The main reasons for higher dissatisfaction across the 3 districts as indicated by the customers are due to following:

  • Less ‘Awareness’ from Utility regarding the attributes ‘Energy Efficiency’ & ‘Consumer Rights’
  • Less communication for ‘Advance notice about disruption’
  • ‘Power Tariff & its variations’ is High

‘Shajapur’ district has higher percentage of customers agreeing towards ‘Privatization’ of Power Distribution compared to ‘Ujjain’ & ‘Dewas’

On being asked if “Service levels will improve

if a private company manages electricity

distribution”, the responses of different

districts were as follows:

  • Shajapur – 44%
  • Ujjain – 39%
  • Dewas – 31%

Across different categories of consumers, over 50% respondents from ‘Commercial’ customers in ‘Dewas’ and ‘Shajapur’ districts agree that ‘service levels will improve if a private company manages

power distribution’.

Approximately 20% respondents from all the 3 districts ‘Neither Agree nor Disagree’ with ‘Privatization of Power Distribution. Also, ‘Agri’ customers have considerably lower expectations (<40%) in ‘Dewas’ & ‘Ujjain’ districts with ‘Privatization’.

Key Findings from ‘Consolidated Report’ of Electric Utility Customer Survey in Madhya Pradesh (MP)

This is the summary of results from the top level analysis, developed using the ‘Consolidated Report’ of all the 9 districts in Madhya Pradesh (MP).

Across all 9 districts, expectations of customers based on certain factors like Customer Service, Power Quality & Reliability and Price are significantly leading to high Dissatisfaction among all categories of customers i.e. Residential, Commercial, Industrial & Agri. Following attributes of above factors need prior attention as suggested by customers:

  • Unplanned / Planned Outages
  • Local Electricity Infrastructure
  • Resolution Billing Complaints
  • Resolution Meter Complaints
  • Service Response Time
  • Value for money
  • Fairness of Price

Customers Agreement Levels of ‘Distribution Privatization’ through franchisee model in all the 9 districts

  • 83% respondents from ‘Bhind’ district agree with positive impact of ‘Distribution Privatization’ followed by 51% respondents from ‘Gwalior’.
  • Only 28% respondents from ‘Sagar’ district agree with positive impact of ‘Distribution Privatization’, which is the lowest of all the districts.

Customers have high expectations from utility to improve the current system & make them fully satisfied

  • Over 55% respondents from all the 9 districts agree that lot needs to be done to improve the current utility system and make them fully satisfied with ‘Bhind’ district has expectation with 91% & ‘Datia’ district has lowest expectation with 56%.

See our earlier blogs for region wise details:

For individual detailed reports on each region, please get in touch with Rahul Bagdia, +91 956 109 4490, rahul.bagdia@pManifold.com.